Retirement tax planning for individuals and families

Keep more of what you saved for retirement.

Large traditional IRA and 401(k) balances turn into large tax bills: required distributions, a surviving spouse's higher single-filer brackets, and your children's tax on what they inherit. I build a multi-year plan from your actual tax return that shows how much to convert to Roth each year, what it costs, and what it saves.

Your plan shows your own numbers, including when converting less, or not at all, is the better choice.

Who this is for

The decisions are largest in the years around retirement.

Retiring soon

Retired, or within ten years

The years between retirement and Social Security are often the cheapest time to convert. A plan makes sure they are not wasted.

Large IRAs

Most savings in pre-tax accounts

Without a plan, required distributions, Medicare surcharges, and a surviving spouse's brackets can push the same dollars into higher rates later.

Business owners

Owners and S corporation shareholders

Salary, distributions, retirement plan contributions, and estimated payments planned together with your retirement accounts.

If you want to leave more to your children or grandchildren, the plan also shows what your heirs would owe on an inherited IRA, so the family pays the least tax overall.

How it works

Three steps, and nothing to change about who prepares your return.

  1. Week 1

    Introductory call

    A short call to understand your situation and whether a plan would help. There is no charge for this call.

  2. Weeks 2 to 3

    Your documents and the analysis

    You upload your last two returns and recent account statements through a secure portal. I build a projection of your federal and California tax for this year and the years ahead.

  3. Week 4

    Your plan and action list

    A written plan in plain language: how much to convert this year, what to do before December 31, and your estimated tax payments. We review it together.

What the plan covers

Every recommendation comes with its cost and its savings in dollars.

Roth conversions

8606

How much to convert this year and in each later year, and where to stop.

Required minimum distributions

RMD

What they will be, when they start, and how conversions now make them smaller.

The surviving spouse

SINGLE

The tax for the spouse who outlives the other, who usually files at higher single rates.

Your heirs

10-YEAR RULE

What your children would owe on an inherited IRA, given their own income and brackets.

Social Security and Medicare

IRMAA

How much of your benefit is taxed, and the Medicare surcharge thresholds to stay under.

Capital gains and losses

SCH D

Gains you can take at the 0% rate, and losses worth harvesting.

Charitable giving

QCD

Whether to give cash, stock, through a donor-advised fund, or from your IRA under the 2026 rules.

Estimated payments

1040-ES · 540-ES

Federal and California payments that cover the plan without penalties.

Pricing

Flat fees. No commissions and no percentage of your assets.

I do not sell investments or insurance, so the only thing you pay for is the advice.

Roth Conversion Plan

A one-time plan

$750 one time
  • One projection from your return
  • This year's conversion amount
  • A multi-year conversion outline
  • One review meeting

Essentials

Retirees and those nearing retirement

$1,500 per year
  • Everything in the one-time plan
  • First-quarter review and year-end action list
  • Social Security, Medicare, and heirs
  • Questions answered all year

Business Owner

Self-employed and partnership income

$2,750 per year
  • Everything in Essentials
  • Midyear projection update
  • QBI and retirement plan contributions
  • Estimated payment planning

S Corp Owner

Shareholder-employees

$4,500 per year
  • Everything in Business Owner
  • Reasonable compensation review
  • Distribution and basis tracking
  • Quarterly estimate monitoring

Current tax clients: if I already prepare your return, contact me directly about pricing for existing clients.

Working with your advisor

Independent tax advice that fits alongside the professionals you already trust.

Already have a financial advisor?

With your written consent, I coordinate with them so your investment and tax decisions line up. Your advisor keeps managing your portfolio.

No investments, no products

I do not manage money, recommend specific investments, or sell insurance. My only compensation is the flat fee you pay.

No referral arrangements

I do not send you to an advisor unless you ask. If you do, I will tell you about any arrangement before you decide.

Your information stays private

Documents come through a secure portal, and nothing is shared with anyone without your signed consent. See the privacy policy.

About

Your plan is prepared by a CPA and Enrolled Agent.
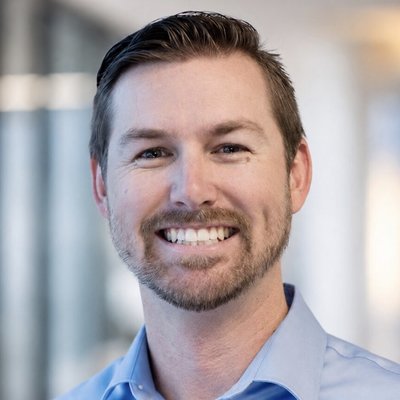
Jeffrey Winger, CPA, EA

Jeffrey Winger, CPA, EA

Founder, Two Returns · Los Angeles

Jeffrey Winger has advised individuals and business owners in Los Angeles since 2003. He founded Two Returns after seeing too many clients approach retirement with large traditional IRA balances and no plan for converting any of it to Roth. His goal is simple: help families keep more of what they have built and pass more of it on to the next generation.

Questions

Common questions

Is a Roth conversion right for everyone?

No. For some households the plan shows that converting little or nothing is best, for example when your tax rate today is higher than it is likely to be later. The plan tells you either way, with the numbers behind it.

Do I need to change who prepares my tax return?

No. I can work from a return prepared by someone else, and your plan can be shared with your preparer so the year-end steps are reported correctly.

What do I need to get started?

Your last two federal and California returns and recent statements for your retirement and investment accounts. After our call, I send a short checklist and a secure upload link.

Do you work with people outside California?

Yes, for federal tax. California tax is included for California residents. If you live in another state, the plan notes where your state's tax would change a recommendation.

What is the difference between the one-time plan and an annual plan?

The one-time plan answers the main question: how much to convert this year and roughly how much in later years. An annual plan updates that answer as your income, the markets, and the tax law change, and includes a year-end action list each year.

Get started

Request a consultation.

Tell me a little about your situation and I will reply within one business day to set up a short call. Please do not include Social Security numbers, account numbers, or tax documents in this form.

We use these details only to reply. See our privacy policy.